Downsizing After The Death Of Your Spouse
It’s what you know you need to do, but the thing you cannot bring yourself to do.
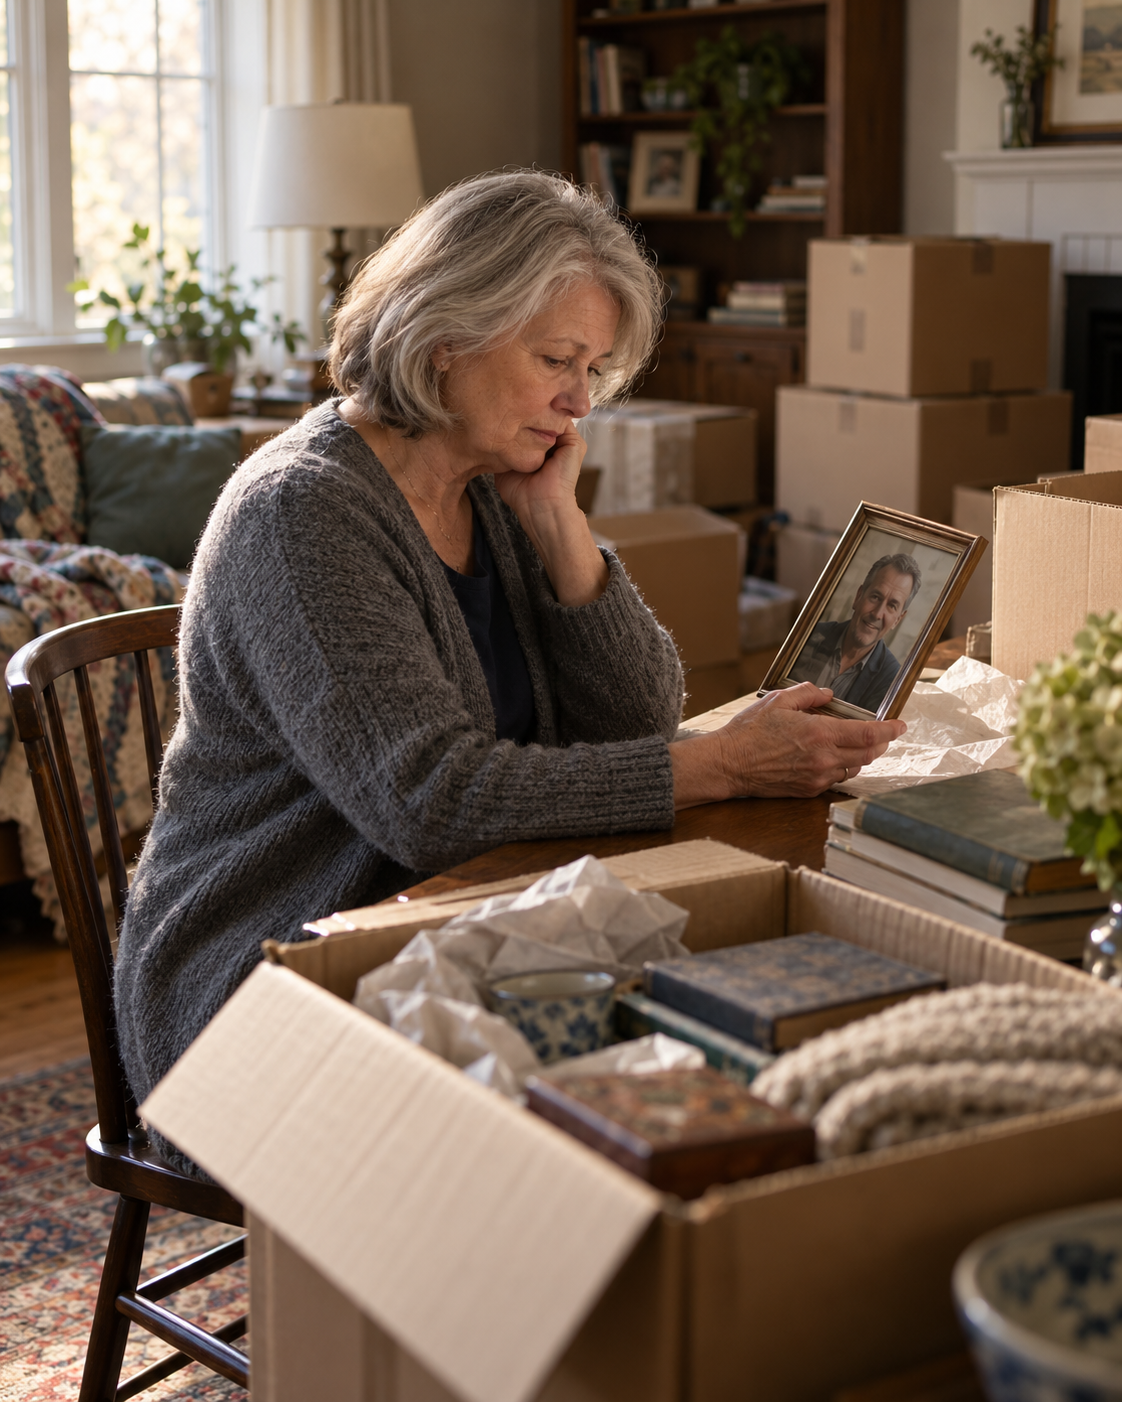
Downsizing and moving after the death of your spouse, especially in your golden years, can be tough when you would be leaving the home you spent your life in with that person, and possibly where you raised your children together.
The children factor is real. You tell yourself, “If I moved, I’d be taking away my children’s home, their connection to their other parent,” but that’s usually not the case at all. The more common scenario is that your kids are talking with one another behind your back about how you should do that exact thing, or, if you have an only child, trust us, they’ve had this conversation with a friend. You’re usually just the last to know because they’re worried about how the idea will make you feel.
Let’s not lie to ourselves. It hurts to leave behind a place we are invested in emotionally, financially, and just outright comfortable in. Most of us could navigate our homes during a blackout without a candle, no problem.
Is it selfish to sell the family home after your spouse dies?
No, you’re not being selfish (even if someone else doesn’t agree with the choice). We covered the worries above, so let me share my own story for perspective.
My mother had the onset of leukemia at 74, a year after she got an all clear from a different cancer. It was a shock. During this, my stepfather left her. The treatment gave her brain fog, mobility issues, you name it. She had already moved into the perfect home for her age: one story, no steps, small, and open. Yet she couldn’t go get her own mail because it was a grouped mailbox at the end of the street. She was a fall risk. She had to use a rollator that she sometimes didn’t use, and I was an endless wreck. If she had been in a home with stairs, lots of rooms, and lots of maintenance, this would have been worse.
Take away the chemo and the illness, and she was 74. She was in the exact type of home she needed to be in. I never had to worry about the things your kids will surely worry about with you. While I did say your kids have likely already accepted that you need to move, we kids sometimes have a hard time accepting that our parents have aged, because it means we have aged. It’s less about you and more about accepting our own reality when we are stubborn, so if you do have a kid taking a long swim down the river of denial, deep down they know that if you decide to sell the family home, it’s what you should be doing.
Why downsizing now is a gift to your kids
My mother bought a manufactured home in a mostly, though not exclusively, senior community because of the layout and the reduced expenses of living there. Before that, she had bought a one-story ranch, but as she and my stepfather (who was a decade older than her) aged, they realized lawn maintenance was getting tough, and going up and down the stairs to the laundry was becoming too much, plus carrying groceries up the stairs from the garage. (If you live in a Pittsburgh house with the washer in the basement, you know exactly what that feels like.) When they moved into the ranch, they downsized quite a bit. When they moved into the next home, they downsized a lot more.
Yet when my mom died eight months after her diagnosis, just days after her 75th birthday, my sister and I had to handle everything she left behind. We laughed and cried (lots) while sorting through her things, but what could have been weeks or months was cut down to days. Only the most important things were there. The little bound book I made her in kindergarten (priceless), a family heirloom drawing a relative in England made from coal in the late 1800s… things that made it easy to choose what to keep and what to part with. Honestly, 99% of it we parted with. Pots and pans, dishes, clothes, furniture. And not a lot of it, either. She’d done all that work for us, and when you’re grieving, being subjected to an attic full of memories, curio cabinets and china closets, boxes tucked into cubbyholes and storage nooks, and knick-knacks that no one wants but everyone emotionally wrestles with parting with, that’s a huge burden.
Case in point: in 1995, I bought my mother these tin camping dishes when I worked at Old Navy (they used to sell that type of thing). They were clearance items. A big tin bowl and plate with some apples on them, a few chips in the enamel, yet she’d kept them for some bloody reason. They obviously meant something to her, and so guess what has been sitting in my dining room for 2.5 years, in a pile of her things I haven’t been able to bring myself to touch? Those tin camping dishes that I do not want. I have no use for them. I feel emotionally guilted into keeping them, even though I can hear her saying, “Get rid of them.” When you downsize and YOU have the say in these decisions, you are giving your family the gift of not carrying that burden later, whether that’s 3 years or 15 years from now.
Can you get a mortgage when you’re retired?
So if you’re reading all this, it’s because you know what you need to do and are looking for reassurance in a choice you have already made. How do you do it?
This is where it can get tricky. If you’re retired and no longer have income outside of Social Security and perhaps pension or 401(k) payments, you might find it challenging to buy a new home if you need to sell your current home first.
First, the good news. Being retired doesn’t disqualify you from getting a mortgage. Lenders count Social Security (including survivor benefits), pensions, and regular retirement account withdrawals as income. Because part of your Social Security usually isn’t taxed, many lenders can “gross it up” when they qualify you, which helps more than people expect. Some loans can even use your savings and retirement accounts to help you qualify (it’s called an asset depletion loan, and it’s a big help for people with a healthy nest egg and a modest monthly check).
The real problem is timing. Most of the money for your next home is sitting in the walls of your current one, and you can’t spend it until you sell. Then once you sell, you need somewhere to go.
How do you buy a new home before selling your current one?
Here are the ways people get around the timing problem.
Open a home equity line of credit before you list
If you own your home outright or close to it, a home equity line of credit (HELOC) lets you borrow against what your home is worth and use that money to buy your next place. When your old house sells, the line gets paid off at closing. The catch is you have to open it BEFORE your house goes on the market, because most lenders won’t open one on a home that’s already listed for sale. So if this is even a maybe for you, set it up now.
Use a bridge loan
A bridge loan is a short-term loan, usually for about a year, that bridges the gap between buying and selling. You use it to buy your new home, and the money from selling your old one pays it off. The interest rate runs higher than a regular mortgage, but you’re only carrying it for a short time.
Unlock your equity with a buy before you sell program
There are programs built for exactly this problem. They unlock the equity in your current home so you can shop for your next one with money in hand, then sell the old house after you’ve moved. Each one comes with its own fees and fine print, so compare them side by side before you sign anything. We have several different buy-before-you-sell options, and we can help you figure out which one fits your situation.
Make an offer contingent on selling your home
You can make an offer on your next home that depends on your current home selling first, but an accepted contingent offer doesn’t lock up the house. Most sellers who agree to one add a kick-out clause, which lets them keep showing the home and taking other offers while yours sits there waiting. If a buyer comes along who doesn’t have a house to sell, you usually get about 72 hours to drop your contingency and buy anyway, or the seller moves on to them. So you can find the perfect one-story ranch, hear that your offer was accepted, and still watch someone else move into it. In a busy market, a lot of sellers won’t take a contingent offer at all. It’s the shakiest option on this list.
Sell first and stay put for a bit
If you sell first, you can negotiate a rent-back with your buyer, where you stay in the home for a few weeks after closing while you close on your next one. Or you can go stay with one of those kids who were talking behind your back. (They did say you should move. Now they get to help.)
Look at a reverse mortgage for purchase
If you’re 62 or older, there’s an FHA program called a HECM for Purchase (that’s Home Equity Conversion Mortgage, because nothing in mortgage lending gets a short name). It’s a reverse mortgage you use to buy your next home. You put down a large chunk of cash, often around half the price depending on your age and interest rates, and that usually comes from selling your current home. After that, there’s no monthly mortgage payment. You still pay the property taxes, homeowners insurance, and upkeep, the home has to be your primary residence, and you’ll go through required counseling before you can get one. It isn’t right for everyone, but for the right person, it means a smaller home with no house payment and more of your savings left in the bank.
Which option fits depends on how much equity you have, what you have in savings, and how much stress you can stomach. If I had to pick one for most people in your shoes, it’s to buy first with a bridge loan or equity line, move into your new home, then sell the old one empty, clean, and staged. A vacant, staged home tends to sell for more, and you aren’t stuck keeping the kitchen spotless for showings while you’re grieving.
What is the 2-year rule when selling a house after a spouse dies?
The 2-year rule lets a surviving spouse keep the married couple’s $500,000 capital gains exclusion if they sell the home within two years of their spouse’s death. Normally, a single person selling their home can exclude up to $250,000 of profit from federal capital gains tax, and a married couple can exclude up to $500,000. As a surviving spouse, you can still use the full $500,000 if you sell within that two-year window, you haven’t remarried, and the two of you met the ownership and residency rules before your spouse passed. Most people have never heard of it, and it can be worth a lot of money.
On top of that, if you owned the home jointly, the half that belonged to your spouse usually gets its tax basis “stepped up” to what the house was worth on the day they died. Pennsylvania isn’t a community property state, so it’s typically just that half, but in plain English, a big chunk of the gain from all those years in the house may already be wiped out. Even if the two years have passed, the $250,000 exclusion plus that step-up covers a lot of people.
You’ve probably heard of the “one-year rule,” the advice to avoid big decisions for a year after losing a spouse. For a lot of things, that’s good advice. Just know that the two-year clock started ticking the day your spouse passed. Before you list, call your accountant or tax preparer and find out exactly where you stand. (I’m a Realtor, and this is a question for a tax professional with your actual numbers in front of them.)
Can you sell the house if your spouse’s name is still on the deed?
In Pennsylvania, usually yes. When a married couple buys a home together here, it’s typically owned as “tenants by the entirety,” which means that when one spouse dies, the surviving spouse automatically becomes the sole owner and the house doesn’t go through probate. You don’t have to rush to change the deed before you sell, and the title company will usually just need a certified copy of the death certificate. If the house was only in your spouse’s name, or it was owned some other way, it may need to go through your spouse’s estate first. I specialize in probate sales, so if that’s your situation, we can help with that too.
How do you downsize your belongings after losing a spouse?
This is the part that keeps most people stuck, so let’s make it smaller.
- Figure out where you’re going first. It’s almost impossible to decide what to keep until you know what will fit. Get the floor plan of your next home (or at least the size and type of home you’re aiming for), measure the furniture you love, and a lot of decisions make themselves. The sectional that seats eleven isn’t going to a two-bedroom condo.
- Start with the easy rooms. The linen closet, the garage, the kitchen gadgets you haven’t touched since the Clinton administration. Save the photo albums and your spouse’s things for later, once you’ve built up some momentum, and do those with someone you trust sitting next to you.
- Sort everything into piles. Keep, give to family, sell, donate, and toss. Then give your kids a date to come claim what they want, and anything left after that gets donated. Habitat for Humanity’s ReStore takes a lot of furniture and household items, and so do local churches and charities.
- Take pictures of what you can’t keep. A photo takes up no room in a curio cabinet. Take a picture of the tin camping dishes, then let them go. (I’m still working on that one myself.)
- Get help. You don’t have to do this alone, and your kids may not be the right helpers anyway (no one fights over a gravy boat like siblings). Senior move managers do this for a living: sorting, donating, selling, packing, and setting up your new home. The National Association of Senior & Specialty Move Managers has a search tool at nasmm.org to find one near you. Most charge by the hour, so ask for an estimate up front. An estate sale company can sell what’s left once you’ve moved.
How do you get an older home ready to sell?
If you’ve been in your home for 30 or 40 years, there’s a good chance it needs some work before it hits the market, and the last thing you want right now is to be calling contractors. Our Listing Concierge service takes that off your plate: we get bids from vetted vendors, and once you approve one, we schedule and track the work, with pay-at-closing options so you aren’t fronting cash. If the house needs more than you want to take on, our Cash+ Repairs program is another route. An investor buys your home as-is, makes the updates, and resells it. You get a first payment at closing and a reserve payment after the investor sells, so you share in the value the updates create without lifting a paintbrush.
Downsizing in Pittsburgh? Let’s map out your move
Someday, when your kids sort through what you’ve left behind, it’ll take them days instead of months, and there won’t be a pair of tin camping dishes in the pile. You already made the hard decision. The rest is logistics.
I’m a Realtor and a licensed mortgage loan originator with One Real Mortgage, so the selling, the buying, and the bridge loan or equity line that connects them can all run through one team. Buy your next home first, move in, and we’ll sell the old one empty and staged, with complimentary home monitoring (check-ins, key holding, and remote monitoring) while it sits vacant. Call me at 412-663-3325 and let’s talk through your options.
Ready to downsize without selling first?
See how a bridge loan or home equity line lets you buy your next home before your current one goes on the market.
The Knox Team, Home of Pittsburgh’s Pawperty Pros. We rescue a shelter pet for every home sold.
Check out this article next